 How-to
Does Homeowners Insurance Cover Roof Replacement?
Last Updated: November 7, 2026
Quick Summary
Yes, homeowners insurance can cover roof replacement when a covered event such as wind, hail, fire, or a falling tree causes the damage. Normal aging and lack of maintenance are usually excluded, so the cause of the damage decides the claim. Good documentation like photos, dates, and a contractor estimate helps support a roof replacement claim.
- Covered perils often include wind, hail, fire, and falling trees
- Damage must be sudden and accidental, not gradual
- Your deductible applies before the insurer pays
- Aging roofs may be paid at actual cash value, reducing the payout
- Photograph the roof and interior from several angles as soon as it is safe
Table of Contents
- When Homeowners Insurance Covers Roof Replacement After Storm Damage
- Does Homeowners Insurance Cover Roof Replacement Due to Age?
- How to Document Roof Damage for an Insurance Claim and Get Insurance to Pay for Roof Replacement
- Frequently Asked Questions
When Homeowners Insurance Covers Roof Replacement After Storm Damage
Yes, homeowners insurance can cover roof replacement, but only when a covered event causes the damage. A storm rips off shingles, the homeowner files a claim, and the coverage question comes down to the cause of the damage. Hail, wind, fire, and falling trees are common covered perils. Normal aging and lack of maintenance usually are not.
Most standard homeowners policies cover "sudden and accidental" damage. That means a single event, like a windstorm that lifts shingles off the roof. If a storm causes the damage, the policy may pay to repair or replace the affected areas. Review your policy's coverage limits and deductible before you assume anything.
Storm damage claims often hinge on documentation. Photos, dates, and a contractor's written estimate all help. Taking photos of the roof and interior damage as soon as it is safe to do so is a helpful step.
- Covered perils often include wind, hail, fire, and falling trees
- Damage must be sudden, not gradual
- Your deductible applies before the insurer pays
Does Homeowners Insurance Cover Roof Replacement Due to Age?
Generally, no. Homeowners insurance does not typically cover roof replacement caused by age alone. Wear and tear, normal aging, and lack of maintenance are standard policy exclusions.
Insurers expect roofs to wear out over time. If you are weighing whether to fix or fully replace an aging roof, our guide to choosing between roof repair and replacement walks through the options. A roof nearing the end of its life may still be repaired after a covered storm, but the insurer may pay based on actual cash value rather than full replacement cost. That means depreciation can reduce the payout. Actual cash value versus replacement cost coverage is worth checking on your policy.
If your roof is old and has no storm damage, the cost of replacement usually falls on the homeowner. Regular inspections and maintenance records can help you plan for that expense and show the insurer the roof was kept in good shape.
How to Document Roof Damage for an Insurance Claim and Get Insurance to Pay for Roof Replacement
Good documentation is the single biggest factor in a successful roof claim. Start the process quickly and keep a clear record of what happened.
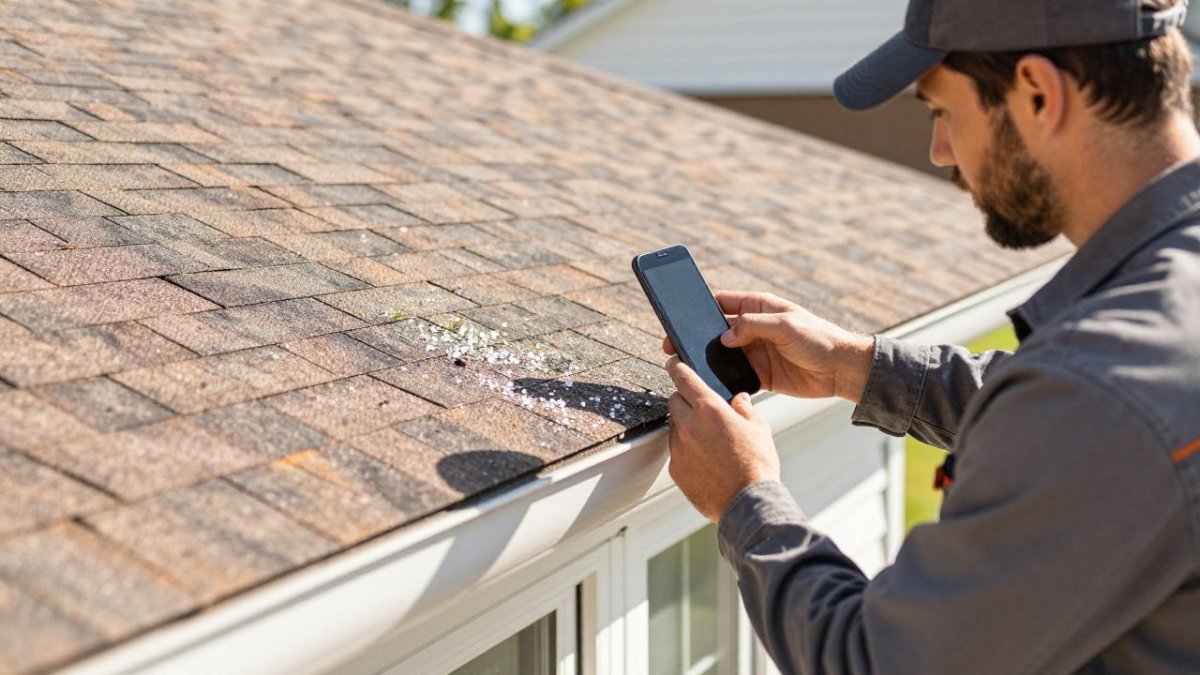
Here is a simple process to follow:
- Prevent further damage with temporary repairs, such as tarping, and keep receipts.
- Photograph the roof, gutters, siding, and interior ceilings from several angles.
- Write down the date and type of storm, such as wind or hail.
- Gather maintenance records that show the roof was cared for.
- Get a written contractor estimate for repair or replacement.
- File the claim with your insurer and request a copy of your policy.
- Meet the insurance adjuster during the inspection and point out the damage.
- Review the settlement offer and compare it to your estimate.
If the settlement seems low, ask the insurer to explain how it calculated the payout. You can request a re-inspection or submit additional evidence. Wait to sign anything until you understand the numbers.
Roof King LLC offers comprehensive insurance claim assistance, and can help you prepare documentation and work with your insurer. You can also read our guide on how to document storm damage for insurance claims for a deeper walkthrough. When you are ready to move forward, contact us to talk through your situation.
The claim process moves through a few clear steps, and each one has a practical purpose.
| Step | What to do | Timing |
|---|---|---|
| 1 | Make temporary repairs such as tarping and keep receipts | Right away, to prevent further damage |
| 2 | Photograph roof, gutters, siding and ceilings from several angles | As soon as it is safe |
| 3 | Write down the date and type of storm | When the storm occurs |
| 4 | Gather maintenance records | Before filing |
| 5 | Get a written contractor estimate | Before filing |
| 6 | File the claim and request a copy of your policy | Promptly after damage |
| 7 | Meet the adjuster and point out the damage | During inspection |
| 8 | Compare the settlement offer to your estimate | After settlement offer |
If your roof took storm damage, start with a roof replacement assessment to see what your coverage may include. Roof King LLC provides expert roofing, repairs, and insurance claim assistance across Lenawee and Jackson County.
Frequently Asked Questions
Does homeowners insurance cover roof replacement due to age?
Usually not. Most homeowners policies treat age, normal wear and tear, and gradual deterioration as excluded causes of loss. A roof that is 20 or 30 years old may still be covered if a sudden, covered event such as a windstorm, hail, or a falling tree damages it. In that case the insurer generally pays for the damage, and the settlement may be calculated on actual cash value rather than full replacement cost, depending on the policy. Review your declarations page and ask your agent how depreciation is applied.
How do I document roof damage for an insurance claim?
Photograph the damage before any temporary repairs, including shingles, dents in gutters and vents, and interior ceiling stains. Record the date of the storm, keep receipts for emergency tarping, and save any weather reports for that date. Get a written repair estimate from a licensed roofer and keep a copy of your policy. Dated, specific documentation makes it easier for the adjuster to confirm that a covered event caused the loss.
How long does a roof insurance claim take?
Timelines vary by insurer and by the size of the loss. Many carriers acknowledge a claim within a few days, schedule an adjuster inspection within a couple of weeks, and issue a decision after the estimate is reviewed. Complex claims or disputes can take longer. Filing promptly and providing complete documentation usually speeds up the process.